Context & Motivation
New technologies often follow the same pattern. At first, insurers do not know enough about the risks to price them, so they raise premiums, restrict cover, or exclude the risk altogether. Over time, shared data, standards, and independent testing make those risks easier to understand. Insurance then becomes more than a way to pay for losses. It starts influencing how products are designed and how safety is maintained.
History offers several examples. After the Great Fire of London, fire insurers paid their own teams to fight fires. Preventing losses was in their financial interest. Shipping insurers gathered in a coffee house where merchants exchanged news, eventually giving rise to a ship register that assessed the condition of vessels. In 1894, fire insurers helped establish a laboratory to test electrical equipment. Car insurers later funded crash tests that changed how vehicles were designed (REF A). In each case, insurers helped develop the tools needed to understand risk, and that knowledge influenced the products they covered.
Insurance depends on being able to measure risk. Insurers usually rely on years of claims data and risks that change slowly enough to model. AI is harder to assess. The same request can produce different answers, models change between versions, and risk of AI varies greatly by use cases even for the same model. New types of harm are also still emerging. There is little historical data to work with, and the risks can change faster than traditional underwriting can keep up.
Cyber insurance faced a similar problem. A wave of ransomware claims pushed the US standalone cyber loss ratio from 47.1% in 2019 to 72.8% in 2020, while US cyber insurance prices rose 130% in late 2021 (REF B, C). Insurers responded by demanding stronger security controls. Market repriced the risk and the raised premiums incentivized stronger risk mitigation. Cyber insurance now has a growing set of standards and procedures for assessing and pricing risk. AI insurance has yet to develop the same foundation.
For now, much of the insurance market is moving in the opposite direction. Optional exclusions for generative AI entered general liability policies in January 2026, and several large US insurers have sought approval for broader AI exclusions (REF D). Some AI labs have reportedly relied on investor funding to help cover settlements because insurance is difficult to obtain (REF E). AI investment has moved faster than the tools needed to underwrite its risks. Without reliable ways to measure those risks, insurers have little incentive or ability to distinguish safer systems from riskier ones.
Some AI risks, particularly those involving national security, may never be commercially insurable. Cyber insurance already offers a precedent for excluding certain state-backed attacks. But that does not mean every other AI-related harm should not be granularly measured and insured. An economy that increasingly depends on AI needs a way to assess and cover the everyday losses that can be quantified. Public or strategic support may change with political priorities and availability of funding and when that day comes, a functioning insurance market needs a more durable basis for assessing risk.
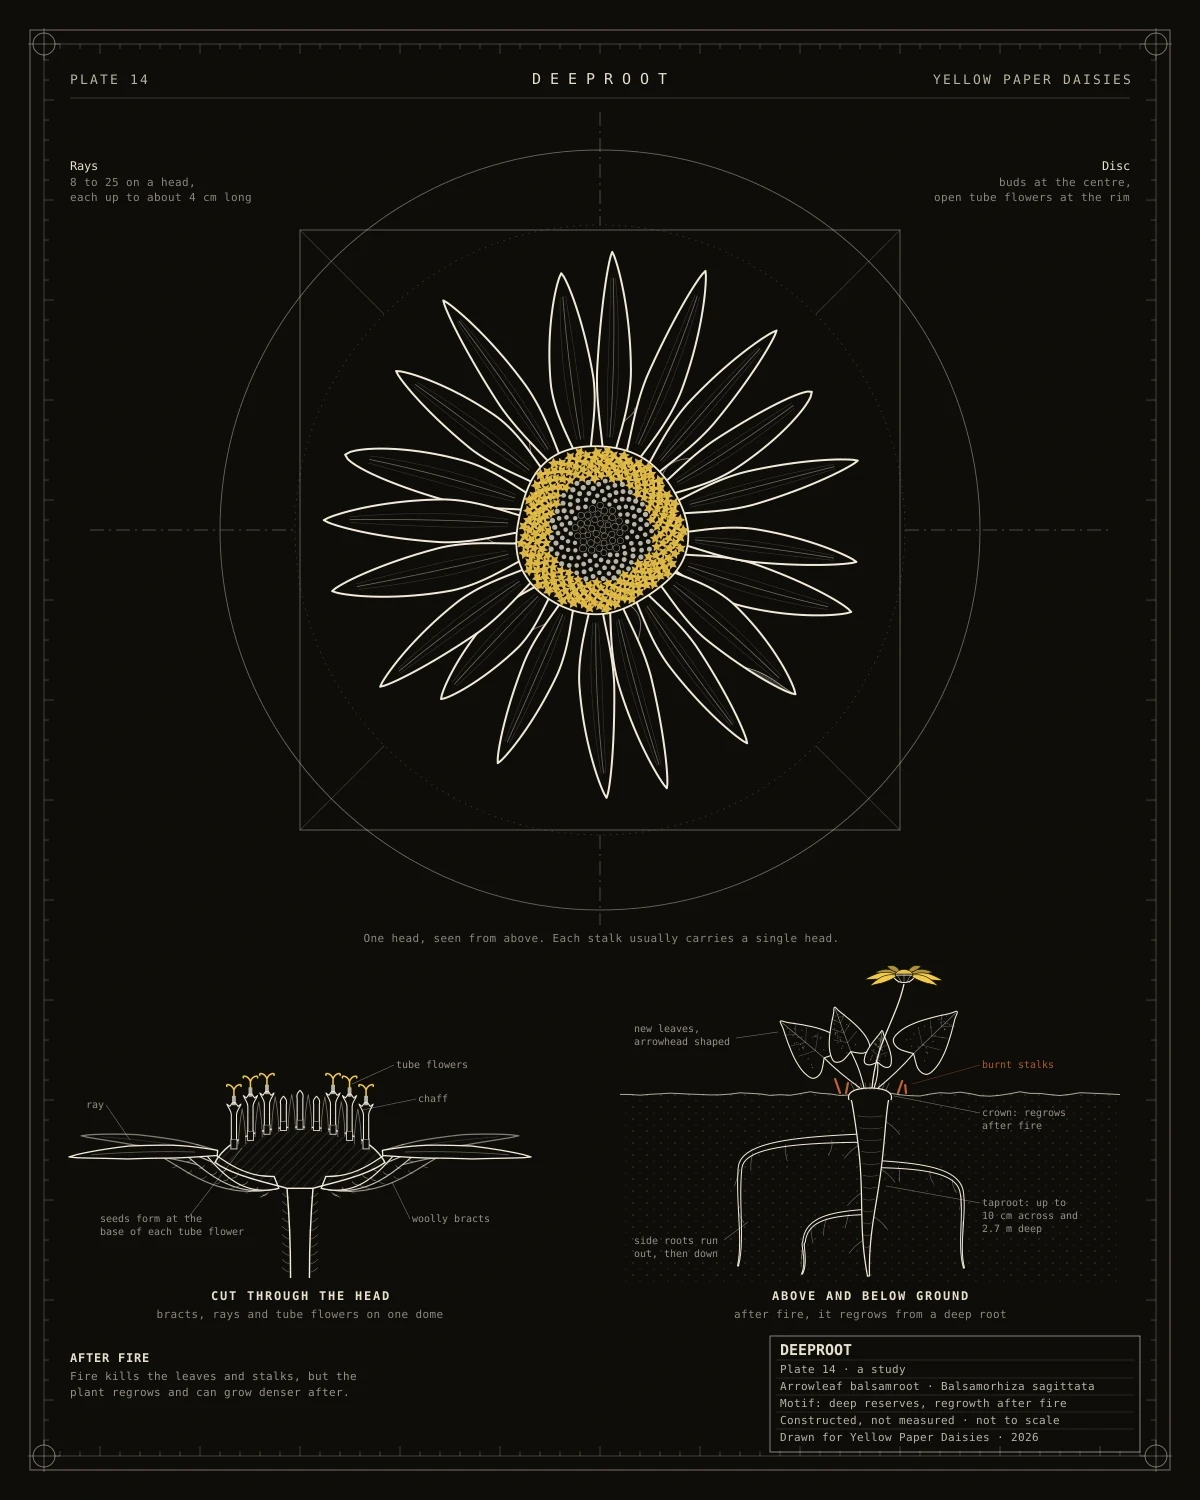
SunAccord sets the shared standard. GoldenMend turns individual harms into rulings. DeepRoot uses those rulings to help price risk, and what insurers learn feeds back into the standard. Together, they create a cycle in which harms inform decisions, decisions inform prices, and prices give organizations a financial reason to build safer AI.
Target Audience
Businesses building products with AI that need insurance for the risks those products create, so they can offer them with greater confidence.
Frontier AI labs that want to demonstrate how their systems manage risk and make them suitable for higher-stakes uses. Models can then be compared measurably not just on technical metrics but on financial metrics too across business use cases.
Insurers that need reliable evidence about AI-related losses and safety controls, so they can assess individual risks rather than exclude AI broadly.
Customer Problems
A travel company launches a booking agent built on a frontier model. Its customers want reassurance, and its board wants insurance. But the company's insurer has added an AI exclusion, while the model provider limits its own liability. Neither party can show what a particular control failure would cost, and there is little claims history to help the insurer estimate the risk.
Insurance can act as an independent check on safety, but only when three conditions are met: someone can be held responsible for a loss, there is a reason to require insurance, and there is enough evidence to price the risk or a credible system of standards and inspections that can help fill the gaps.
For much of AI, these conditions are not yet in place. The underlying problem is that AI risks are not measured consistently enough to be priced and insured with confidence. Insurers too do not have the mechanisms to reliably measure these novel risks by themselves with data that is available to them.
Hypothesis
- Limited liability: Provider terms often limit liability, while the EU withdrew its proposed AI Liability Directive. As a result, people harmed by AI may face uncertainty about whether they have a viable claim and how to pursue it (REF F, REF G).
- No requirement to carry cover: Frontier labs may supply models used by other businesses without being the company directly serving the end customer. There is not yet a general requirement for these labs to carry insurance for the harms their models may contribute to.
- Businesses struggle to find cover: Companies selling AI-powered products need protection against potential losses, but insurers may offer limited cover or exclude AI-related risks.
- Too little evidence to price risk: There is no mature, shared record of AI losses or consistent way to measure risk. Building both the evidence and the measurement methods will take time.
- Controls are difficult to compare: Safety controls vary in what they prevent and how effectively they work. Without consistent evaluation, insurers cannot reliably compare one system with another.
- Residual risk is unclear: Even after safeguards are introduced, it is difficult to quantify the risk that remains.
- Models keep changing: A model may respond differently to the same request, and its behaviour can change between versions. Annual insurance pricing may not reflect those changes.
- Harms remain hidden: Companies may not disclose incidents, and many AI-related risks are too new to have established reporting practices.
- Losses can be correlated: A single model failure could affect thousands of customers or businesses at once, creating a concentration of claims.
- Sharing evidence creates exposure: Labs may be reluctant to share safety and incident data if it could reveal vulnerabilities, expose confidential information, or be used against them in a dispute.
- Not every harm appears in a claim: Some harms are difficult to express in financial terms, and many affected people may never file a claim.
Solutions
- Build measurement together: AI labs and insurers develop monitoring, data collection, and risk-evaluation methods together, with independent evaluators checking the results. Labs demonstrate how their systems perform rather than relying on assurances alone.
- Put a price on residual risk: Evaluate controls according to the harms they prevent, then estimate the risk that remains after safeguards and compensating measures are in place. The result is a range that reflects uncertainty, rather than a single number presented as certainty. Measurements will become more accurate as harms become known over time, which will reduce uncertainty.
- Monitor continuously and price fairly: Labs share agreed telemetry and evaluation results through a secure channel, without sharing model weights. As with usage-based car insurance, premiums can reflect observed behaviour and risk. Adjustments happen at renewal or within tiers whose terms are agreed in advance (REF H).
- Model realistic scenarios: Use scenario models to test how failures could spread across systems and affect many people at once. Calibrate those models annually against SunAccord's record of reported harms and GoldenMend's rulings, including evidence of losses that are not purely financial.
- Connect claims to rulings: GoldenMend gives affected people a route to a decision about responsibility. Insurers use those rulings to assess covered claims, subject to the policy terms. Retained logs, model versions, and reproducible tests help establish what happened. Straightforward, low-value claims can follow a faster payment process where coverage and eligibility are clear, without requiring a full fault determination in every case.
- Make evidence safer to share: Establish clear rules for sharing incident data and evaluation results. The aim is to improve risk assessment and prevent repeat failures, not to turn every disclosure into an opportunity to assign blame.
- Reward safer behaviour, not blanket refusal: Systems that demonstrate effective safeguards and lower measured risk should be eligible for lower premiums. A model should not automatically appear safer simply because it refuses more requests; evaluation should account for whether it remains useful while managing risk.
- Make appropriate cover part of participation: SunAccord members carry insurance proportionate to their scale and exposure, using layers of cover where appropriate. Risks that cannot be insured at an acceptable level must be reduced, contained, or kept out of uses where the potential losses would be unacceptable.
- Extend cover to the businesses building on AI: Once a model's risks can be measured more reliably, insurers can develop cover for the businesses that incorporate it into products and services. This gives those businesses a clearer way to manage their own exposure.
- Feed insurance evidence back into the standard: Lessons from claims, rulings, monitoring, and underwriting return to SunAccord. The shared standard can then evolve as evidence reveals which controls work, where failures persist, and which risks remain difficult to measure.
Outcome
- Insurance becomes an additional market incentive for AI safety. It complements laws and regulators by giving organizations a financial reason to measure and reduce risk.
- AI risk is more granularly priced in. Claims, evaluations, and independent assessments help distinguish demonstrated safeguards from unverified assurances.
- Insurers have an incentive to prevent losses. As in fire safety, electrical testing, and vehicle safety, better measurement can make prevention financially worthwhile, not just paying claims after something goes wrong.
- More high-stakes uses become insurable. When risks can be assessed and managed, businesses have a clearer path to deploying AI in settings where reliability matters.
- Each harm improves the shared understanding of risk. Rulings and incident data can reveal recurring failures and help improve evaluations across participating systems.
- Safer systems can pay less. When lower risk is demonstrated through credible evidence, insurance pricing can reward it.
Appendix
- Read about early fire insurers, the ship register, electrical testing and crash tests
- Read the loss ratios and the price index
- Read about the new exclusions and insurers seeking approval
- Read the report
- Read about the war exclusion case and the market bulletin
- Read an example of consumer terms
- Read about the withdrawn directive
- Read about usage based insurance